Finding
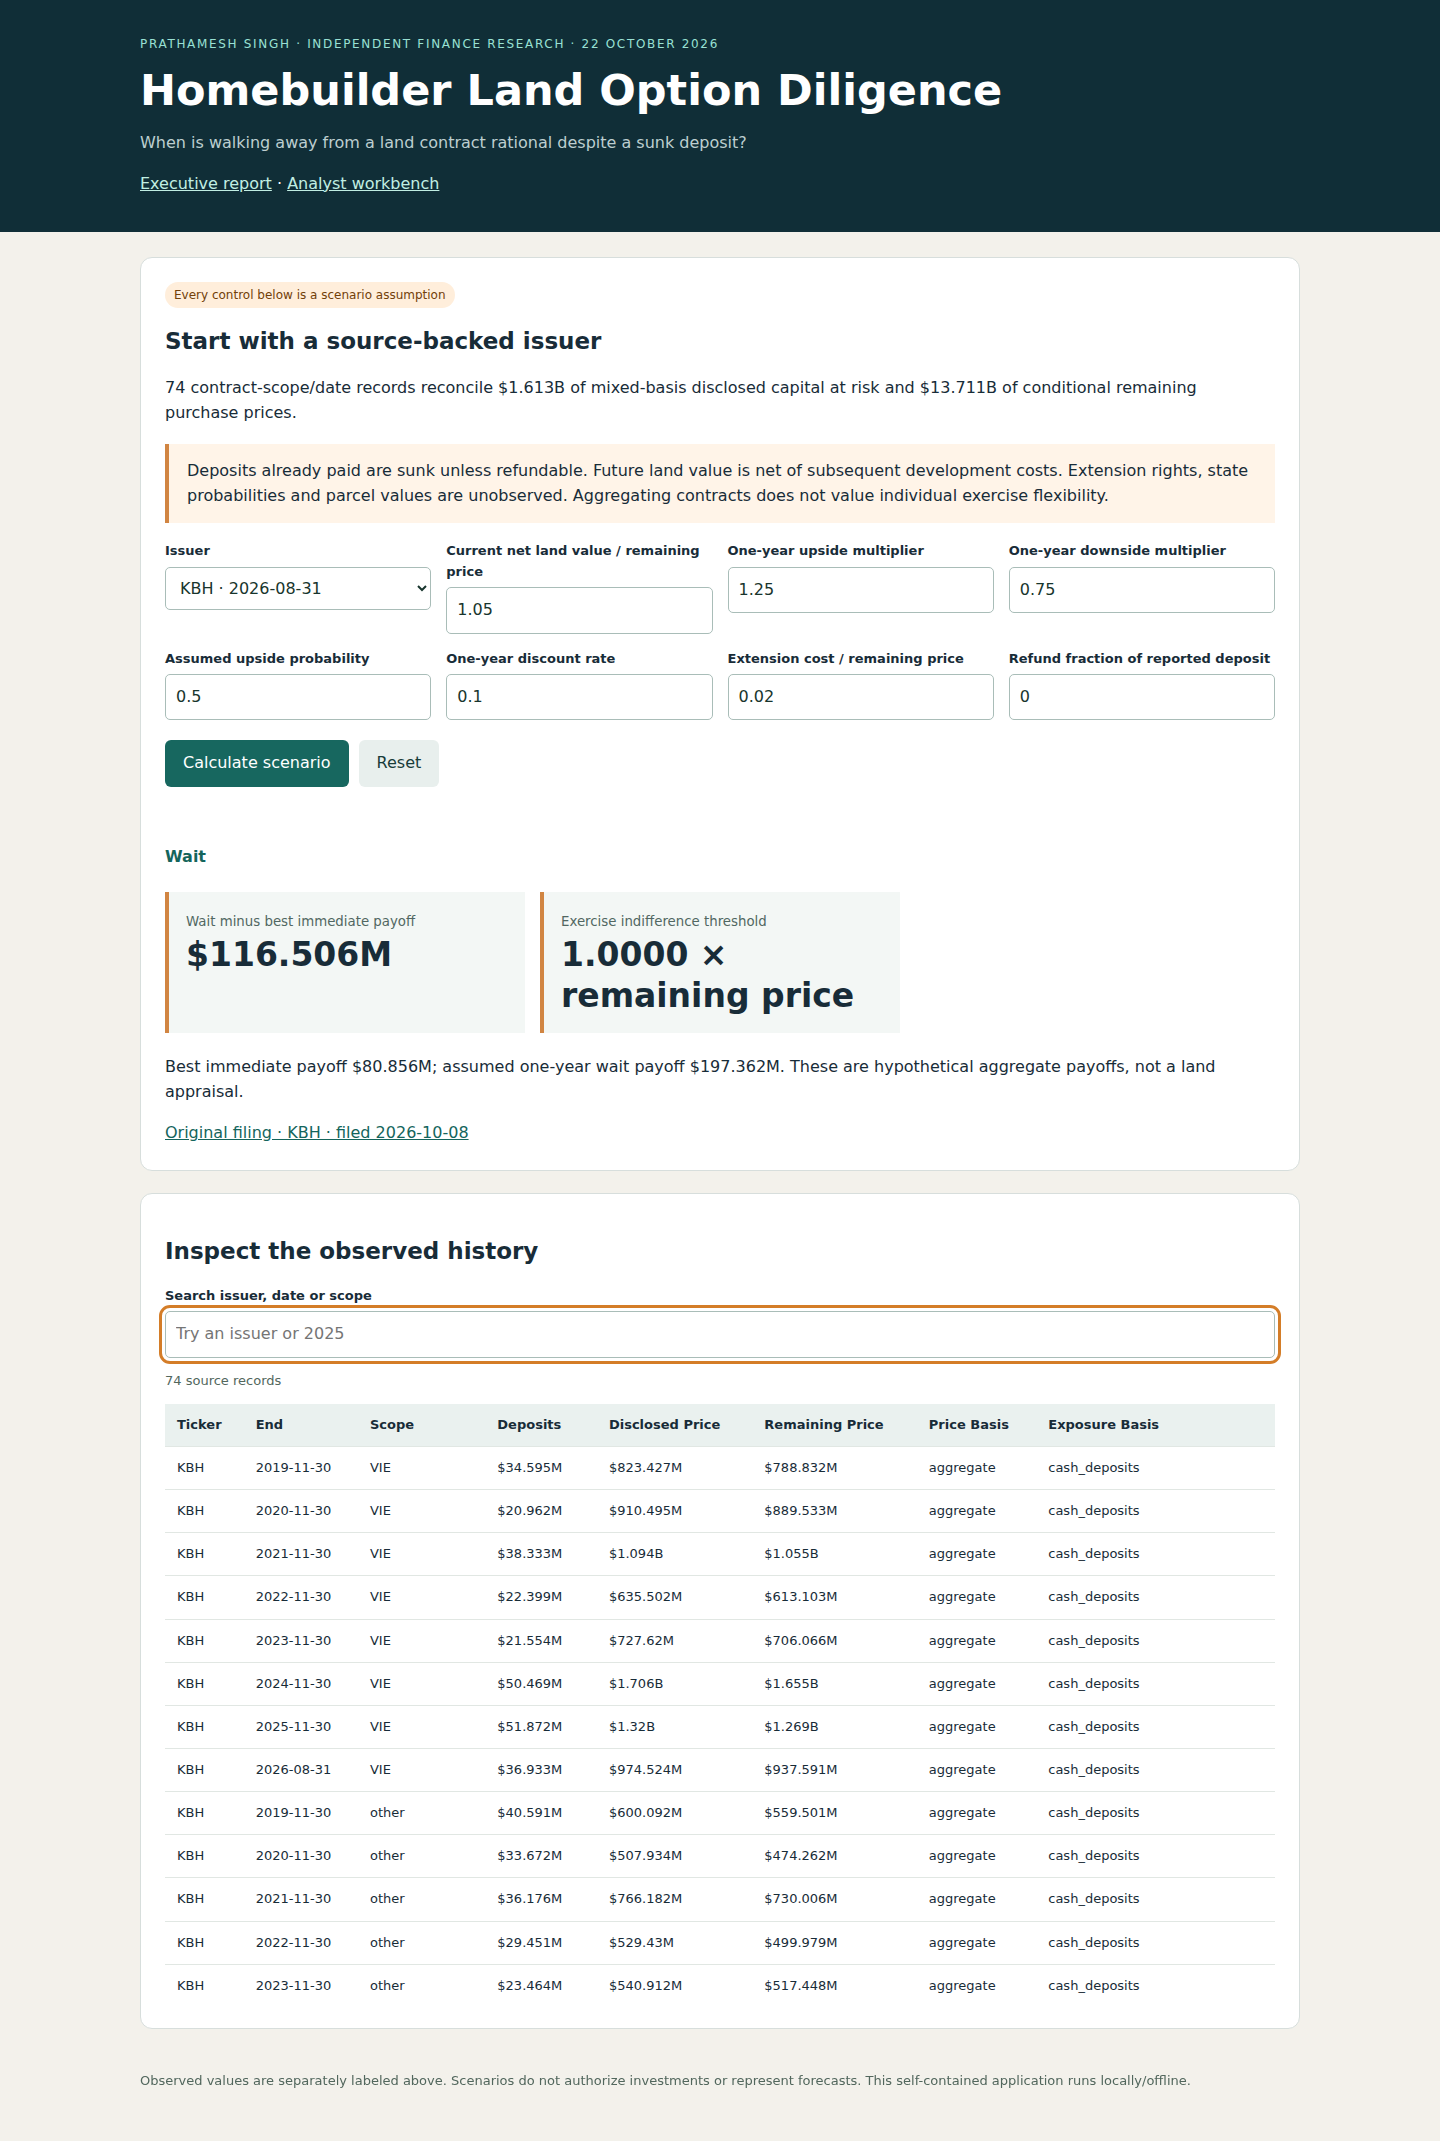
The retained disclosures reconcile $1.613 billion of mixed-basis capital at risk and $13.711 billion of conditional remaining purchase prices. Contract scopes and dates differ. The exercise, wait and abandon scenarios use hypothetical values and terms rather than estimated parcel option values.
Why it matters
Request tract-level values, refund rights, extension terms and minimum purchase schedules. A sunk deposit is relevant exposure, but does not by itself make a future purchase attractive.
Who could use this
Homebuilder acquisition and finance teams reviewing deposits, optional future outlays and contract boundaries.
Data and scope
74 contract-scope/date records from 24 original SEC numerical filing snapshots. Disclosed capital-at-risk bases and observation dates differ by issuer.
How the analysis works
A source-linked contract register reconciles total and component scopes. Two-stage exercise, wait and abandon choices are evaluated in 243 assumed scenarios and 27 refund sensitivities.
Limits of the evidence
Parcel values, probabilities, discounts, extension costs and refundability are assumed. The scenarios are not estimated option values or company-specific acquisition recommendations. A reused accounting tag does not establish a legal refund right.