Finding
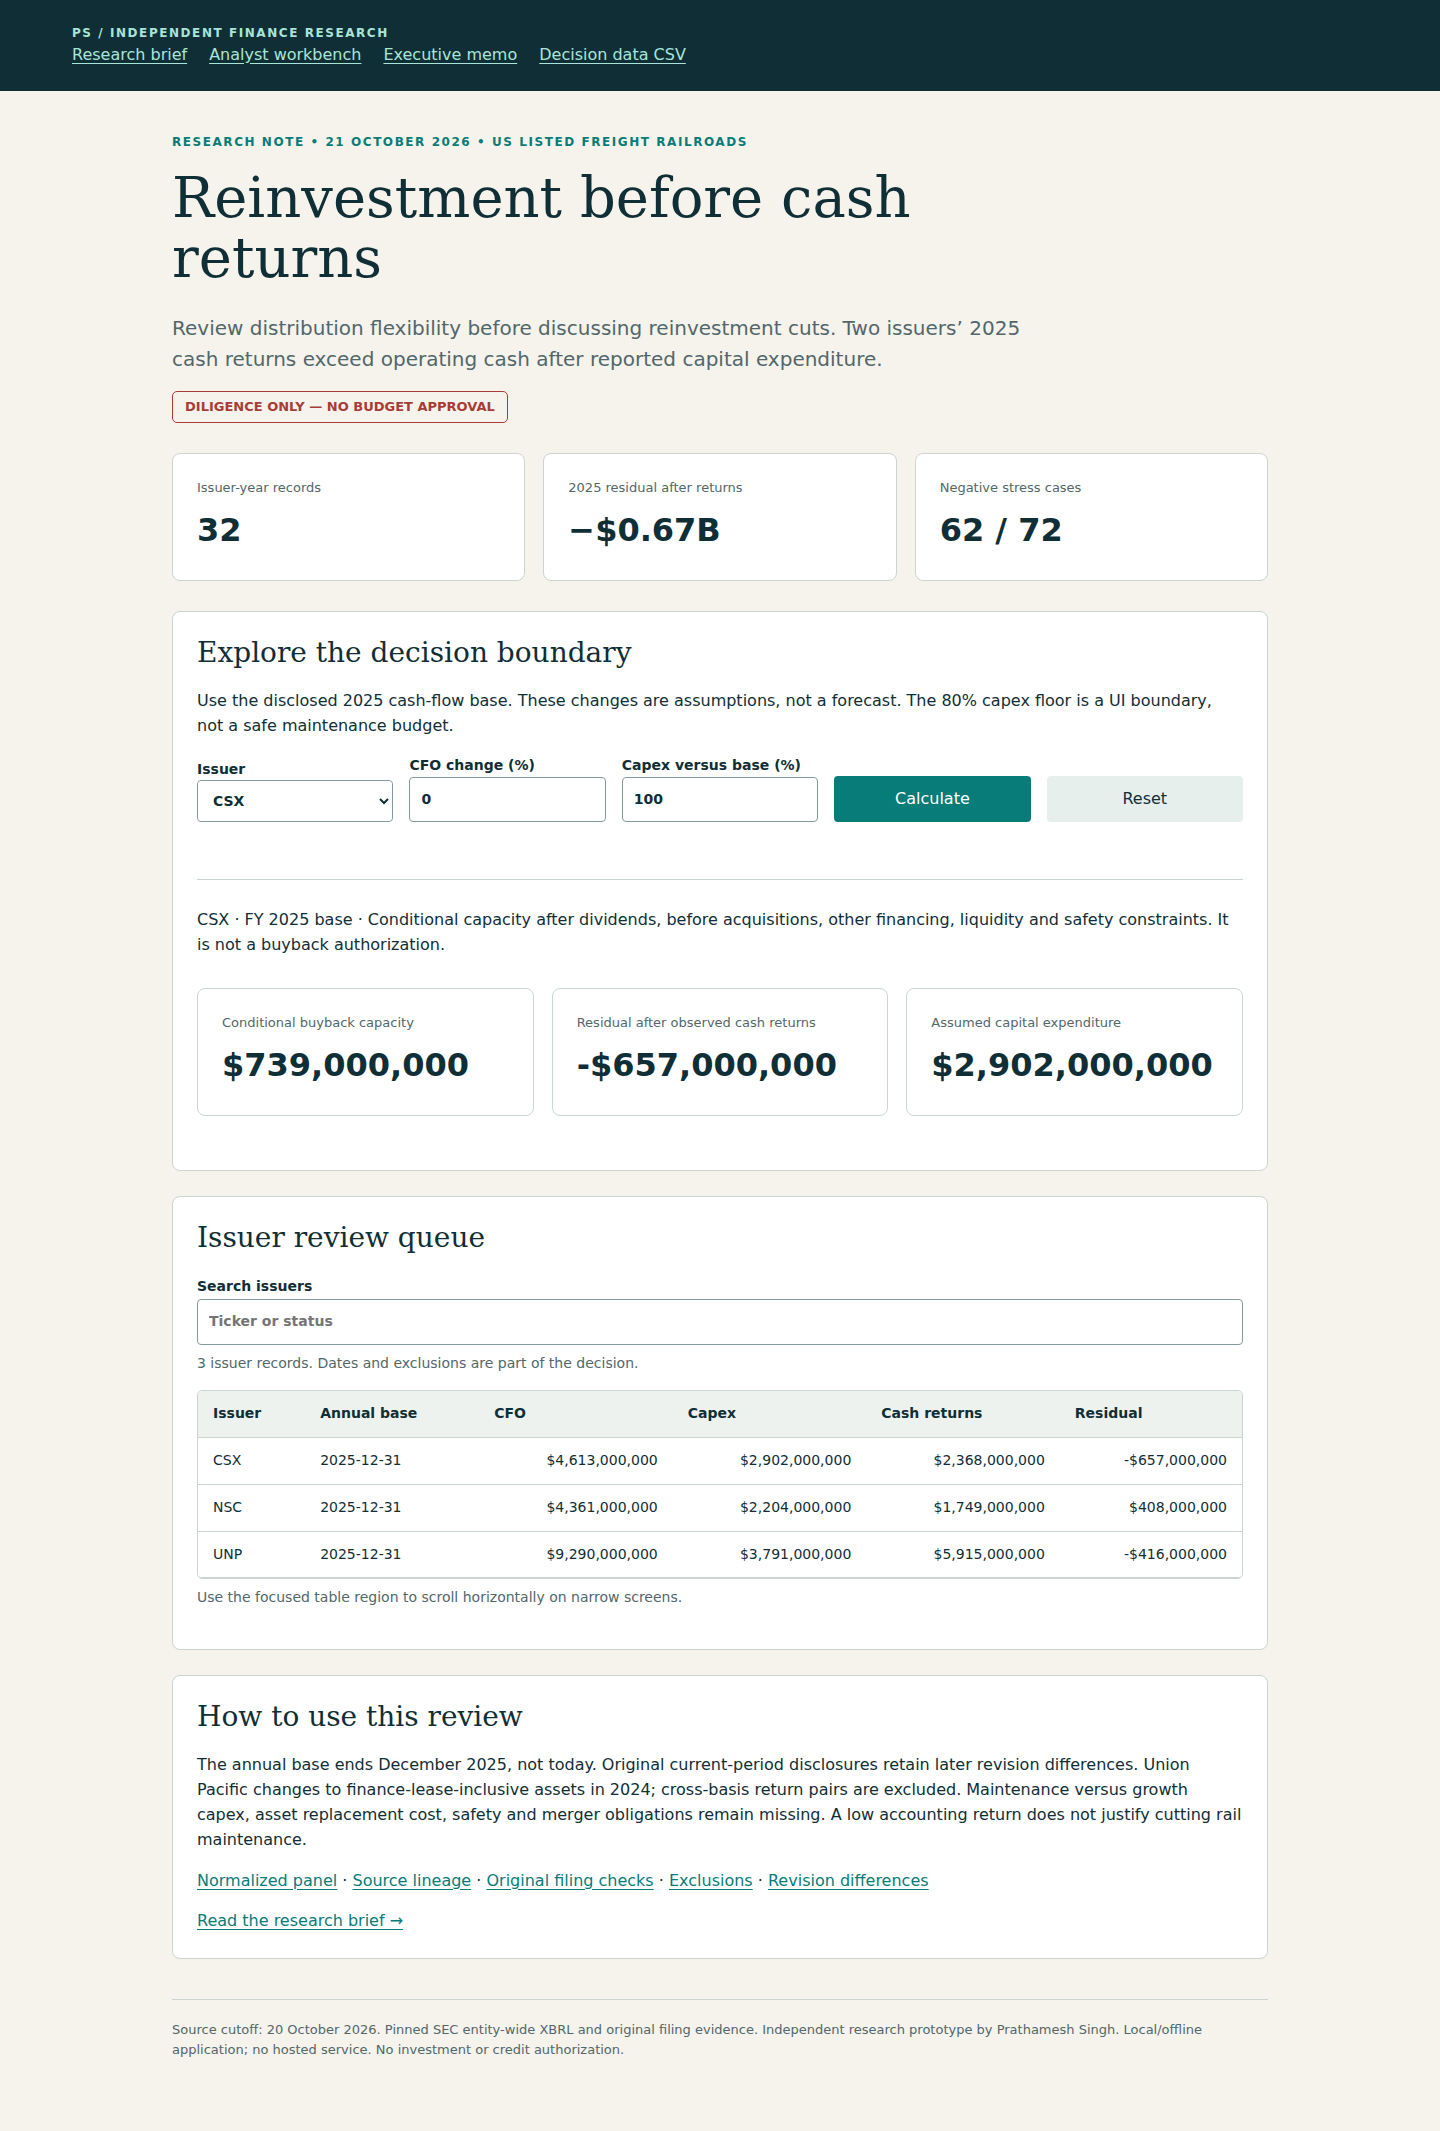
Across Union Pacific, CSX and Norfolk Southern in FY2025, operating cash totals $18.264 billion, cash PP&E capex $8.897 billion, and dividends plus repurchases $10.032 billion. The specified residual is −$665 million, with two issuers showing a negative subtotal.
Why it matters
Review distributions alongside maintenance, safety and committed growth spending. Other cash sources and uses belong in the actual treasury plan before changing investment or shareholder returns.
Who could use this
Corporate finance and treasury teams reviewing distributions against capital commitments.
Data and scope
32 admitted company-years and 256 SEC source figures. Latest comparisons use a coherent FY2025 across Union Pacific, CSX and Norfolk Southern.
How the analysis works
Original-filing reconciliation, a cash-return subtotal, reverse CFO stress and three-year coverage. Net/gross productive-asset and tax/hurdle sensitivity expose the limits of accounting-return proxies.
Limits of the evidence
Cash is fungible: this subtotal does not show which payment was debt-funded or establish a current funding deficit. Fixed-asset proxies are not issuer ROIC. Safe capex cuts cannot be inferred from the scenario controls.